News
AI Deployment Gets Wider; Earnings Quality Becomes the Test
New llama.cpp and MLX releases reached harder deployment details, while Zoom's results showed why earnings quality, not headline profit, is the test.
Read More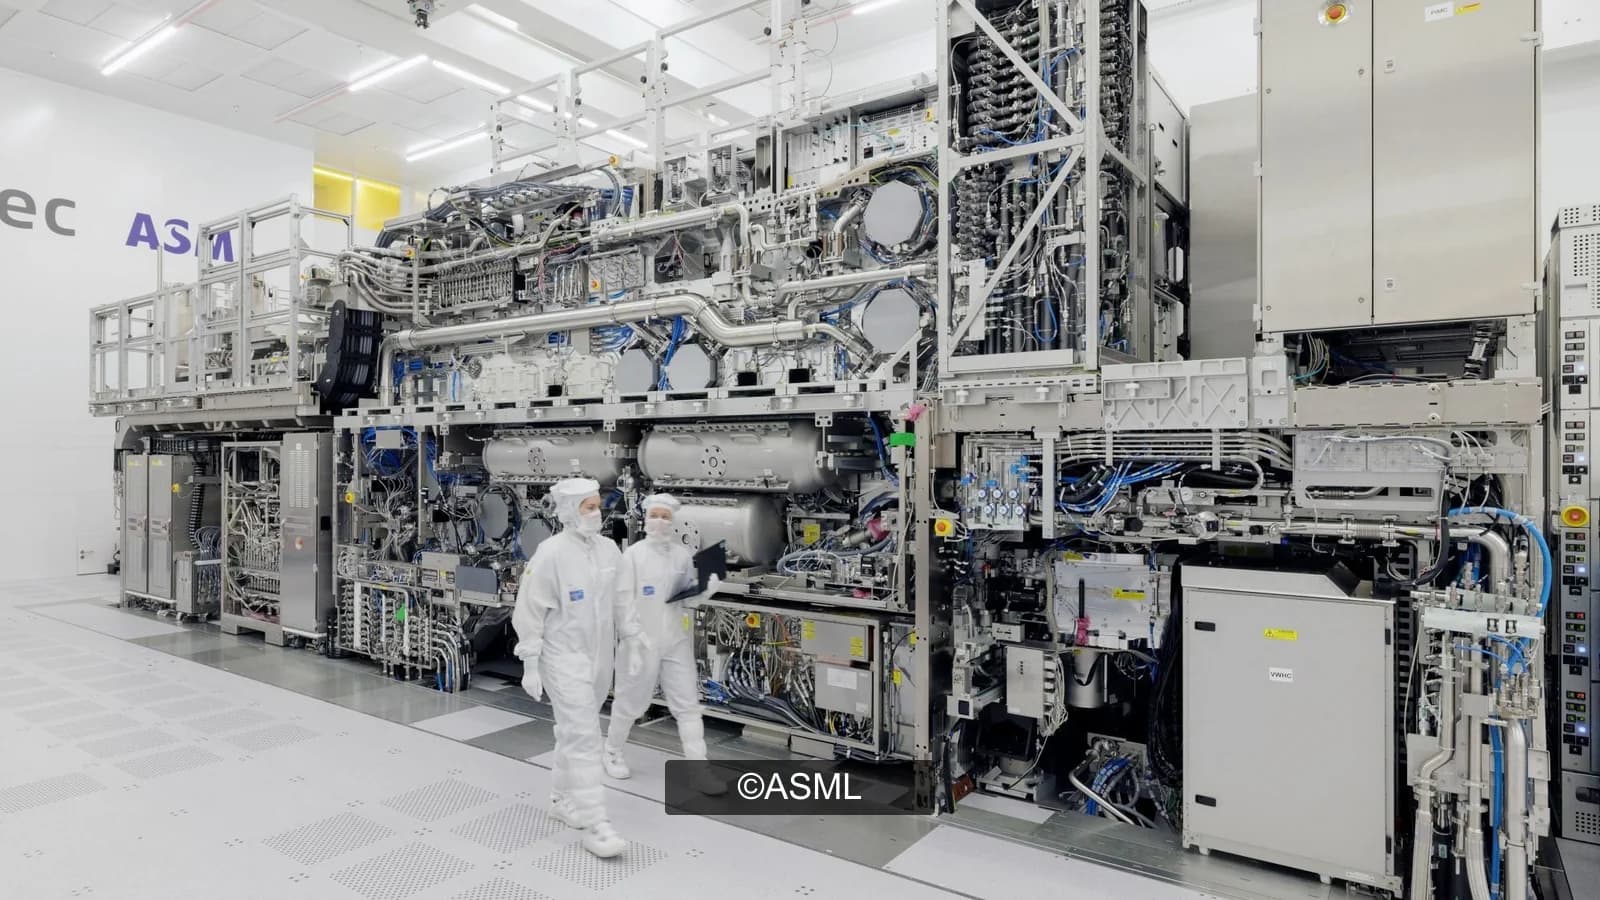
ASML says its planned supply cannot fully meet customers' demand in 2027 and 2028, despite substantial current earnings.
ZharfAI ResearchOctober 15, 20267 minutesSource: ASML
NVIDIA's new simulation tools may shorten engineering work, but selected-task speedups do not establish additional factory output. A survey of semiconductor professionals points to staffing constraints, while US inflation adds a separate financial consideration. This edition examines what each record actually measures: equipment capacity, reported profit, computation time and consumer prices. The useful next evidence is a firmer manufacturing commitment and validated performance in real workflows, not an assumption that software has already closed the supply gap.
ASML said on October 14 that its currently planned supply would not fully cover customer demand in either 2027 or 2028. It is examining a larger expansion for 2028, not announcing that the extra capacity has already been secured. For a chipmaker planning a new production line, the consequence is concrete: a strong equipment budget does not guarantee a delivery slot. The forecast comes from ASML management and depends on customers' plans; it is not a finding that every kind of chip will be scarce. Nevertheless, it places equipment availability alongside financing as a constraint worth tracking.
The scope matters. ASML's earlier plan called for 2027 capacity in low-NA EUV and immersion DUV equipment to rise 30% from 2026, with a further 30% increase under investigation for 2028. Those are particular lithography categories, not a promise about all products or High-NA machines. The latest statement asks whether the second expansion should go further. ZharfAI's reading is that the decision still needs to become a production program: suppliers, assembly space, trained staff and delivery commitments have to support it. A percentage without the relevant product and baseline cannot tell a customer how many usable tools it will receive.
The financial statement provides a different kind of evidence: results already recorded. For the quarter ended September 27, ASML reported €11.662 billion in sales, €5.173 billion in operating income and €4.960 billion in net income under unaudited US GAAP accounts. Service and field-option sales were €3.289 billion. Management attributed strength in that business to productivity upgrades. This is an important alternative to waiting for a new machine: improving equipment already installed may help a factory obtain more from its existing footprint. It also makes services and upgrades economically significant rather than a footnote to new-system sales.
The net-income figure needs one qualification. The income statement separately records a €509.7 million gain on equity investments below operating income. It should not be described as revenue from selling lithography machines, and the disclosure does not justify calling it cash received or assuming it will recur. Nor would subtracting that pre-tax gain directly from net income produce a defensible adjusted profit: tax effects and other accounting items matter. The practical comparison is between clearly labeled reported measures, not an improvised earnings number. A large profit can coexist with a supply constraint without establishing either the cash available for expansion or its completion date.
NVIDIA's October 14 SEMICON West announcement addresses another part of the production problem: engineering computation. Its early-access cuPotential library is intended to accelerate atomic and molecular simulation, with AI agents able to run and evaluate experiments. NVIDIA reports an additional two- to threefold speedup in early tests on workflows already optimized for GPUs. Lam Research plans to integrate NanoVDB into SEMulator3D, with up to 30-fold acceleration for selected wafer-etch modeling tasks and a release targeted for the end of 2026. These are supplier-reported, workload-specific claims, not independently established gains in finished-wafer output.
A faster simulation can still be valuable without manufacturing another wafer by itself. Consider an engineer comparing possible etch recipes: a shorter calculation may allow more candidates to be rejected before a physical trial. The benefit would be less engineering time or fewer unsuccessful experiments, provided the model remains accurate. That is different from accelerating the etching chamber, qualifying the chosen process or installing another production line. A buyer evaluating the software should therefore ask which calculation was timed, whether setup and validation were included, and whether comparable accuracy was maintained. Multiplying an entire factory's output by a benchmark speedup would answer none of those questions.
EMD Electronics' October 13 survey release offers a useful counterweight to a software-only explanation. Among 200 respondents surveyed in September, 75% identified skilled labor as the biggest barrier to accelerating domestic investment; 24% reported using AI in capacity planning and 14% in factory scheduling. IntelliSurvey used targeted telephone and expert-panel recruitment. This is a company-commissioned sample, not a representative census of semiconductor factories, and EMD sells materials to the industry. Its findings support a narrower point: the respondents describe staffing and planning problems alongside technology adoption. They do not quantify how much additional capacity AI has actually delivered.
The operational question is where a specific factory loses time. If engineering calculations are the bottleneck, faster simulation could help; if a tool is waiting for installation specialists, that same improvement may leave the delivery schedule unchanged. These are illustrative cases, not diagnoses of an identified ASML customer. They explain why software and physical investment can complement each other without being interchangeable. A credible project estimate would connect the saved engineering hours to the next constrained step and include the cost of computing, integration and checking results. Otherwise, a striking speed claim can conceal a small effect on the date when a customer receives working equipment.
The separate macroeconomic signal is the September US consumer-price report, released October 14. BLS recorded a seasonally adjusted 0.6% monthly rise in headline CPI and a 3.7% increase over twelve months. Excluding food and energy, the corresponding rates were 0.3% and 2.6%. Those figures describe household prices, not semiconductor equipment costs, and they establish neither a future central-bank decision nor the cause of a particular share-price move. For a long-lived factory project, their relevance is uncertainty around the broader financial environment. They should prompt explicit financing assumptions, not be inserted as a substitute for a supplier quotation.
What would change the assessment? For ASML, a firmer capacity commitment with product scope and delivery milestones would be more informative than another expression of demand. For the Lam software, the targeted year-end release and tests on customers' actual workflows would show whether the selected-task gain survives integration. For a factory, the decisive evidence would be accepted tools, qualified processes and staffing sufficient to operate them. Demand forecasts can be revised downward as well as upward; efficiency can reduce the equipment needed for a given task. Neither possibility is settled by this week's announcements.
The conclusion is not that software cannot relieve manufacturing constraints. It is that the relief must be traced to a particular step and measured in the right units. ASML has disclosed a supply-planning problem despite substantial current earnings; NVIDIA has described ways to reduce some engineering work. Those statements can both be true. Treating them as evidence of an already solved shortage would discard the most useful information in each. This edition uses a 48-hour window ending October 15 at 09:01 Tehran time to include EMD's related October 13 SEMICON release; the remaining records were published within the latest 30 hours.
Cover: ©ASML. Editorial file photograph of High-NA equipment in a Veldhoven cleanroom, cropped for this page. It illustrates the machinery, not a newly completed expansion or the low-NA EUV and immersion DUV capacity discussed above.
TagsASMLSemiconductor CapacityAI SimulationEarnings QualityUS Inflation
New llama.cpp and MLX releases reached harder deployment details, while Zoom's results showed why earnings quality, not headline profit, is the test.
Read More
US stocks lost about $6 trillion in 45 days. A widely read analysis calls it a correction, not a burst AI bubble. We checked each claim against filings and market data.
Read More
Thinking Machines' 26.4B open model runs its middle layers three times per token and fits on a 32GB Mac. We read its checkpoint, the independent scores and its Persian token cost.
Read MoreIf this note maps to a real system in your organisation, start with the services page or a shipped case study.