News
Did the $6 Trillion Stock Sell-Off Burst the AI Bubble?
US stocks lost about $6 trillion in 45 days. A widely read analysis calls it a correction, not a burst AI bubble. We checked each claim against filings and market data.
Read More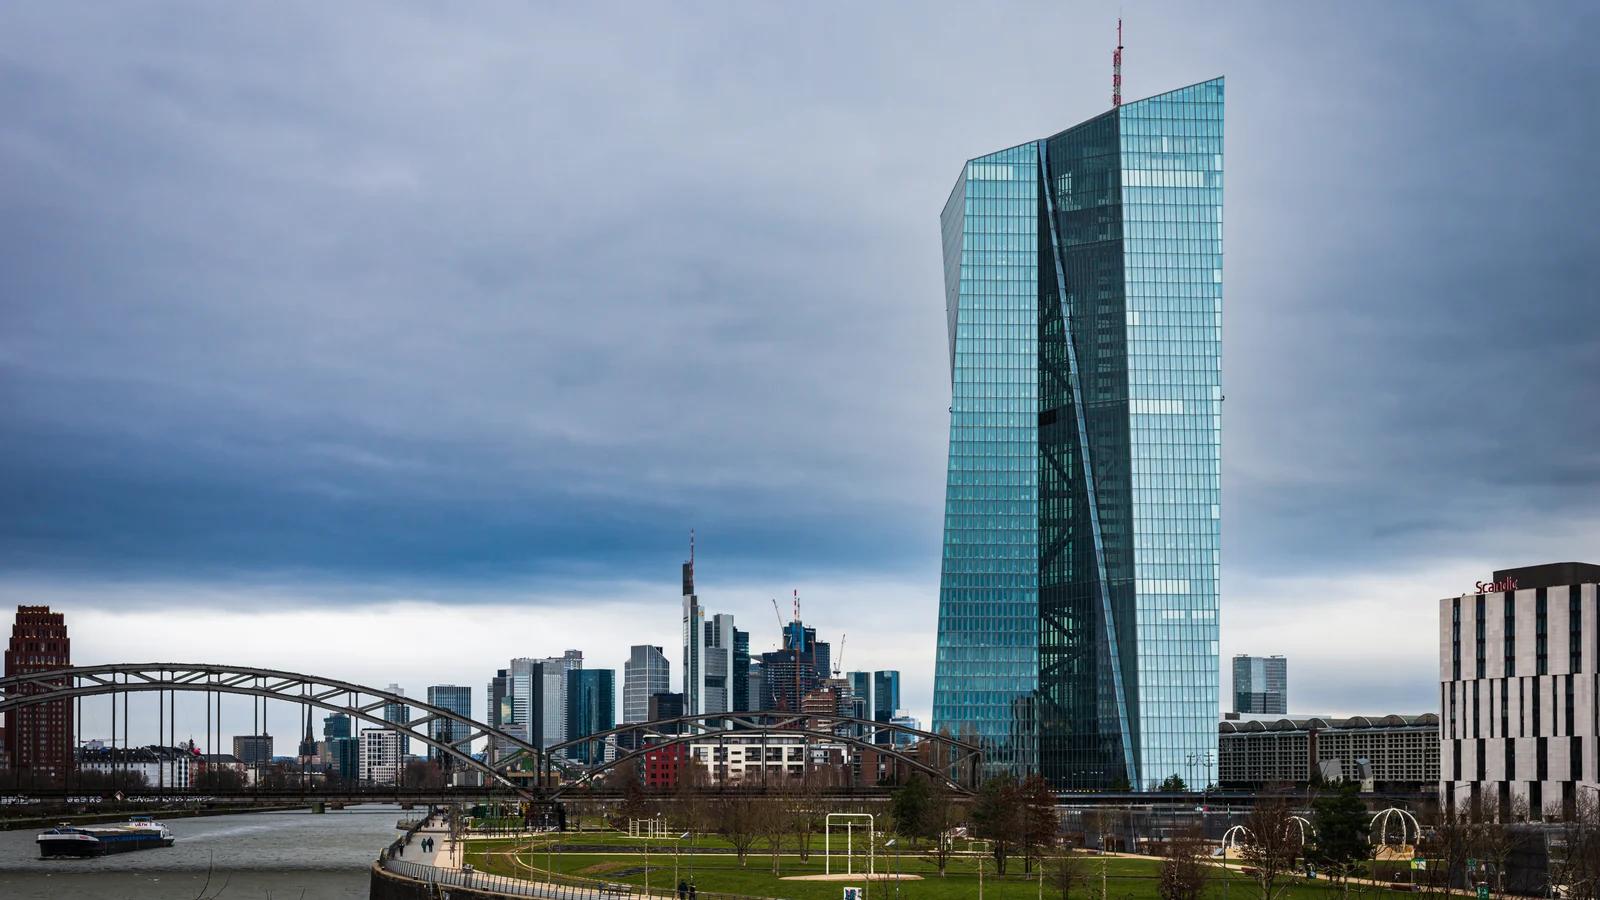
The European Central Bank warns that debt-funded AI infrastructure could carry potential losses beyond equities into bond markets.
ZharfAI ResearchNovember 19, 20267 minutesSource: European Central Bank
Newly published Federal Reserve minutes also expose concern about complex financing arrangements. Meanwhile, Nvidia’s strong sales show real demand, and OpenAI’s lower prices for a new model could benefit customers. The issue is not whether that demand exists: a supplier’s revenue today does not necessarily guarantee a buyer’s repayments years from now. ZharfAI separates delivered sales, planned manufacturing capacity and model-use costs, without mistaking central-bank warnings for certainty of a crisis.
The European Central Bank warned on November 18 that a reversal in enthusiasm for artificial intelligence could reach beyond technology shares. As more AI infrastructure is financed with debt, losses could spread into bond markets. The consequence is concrete: evaluating an AI expansion now requires asking who financed it and who absorbs a disappointing return, not merely whether its shares look expensive. This is a warning about a transmission mechanism, not a prediction that a market crash is inevitable.
ZharfAI’s interpretation is that strong chip sales and concern about financing can both be justified. A manufacturer can deliver a product and recognize revenue today while its customer still needs several years of business to recover the purchase price. The seller’s accounts do not establish every buyer’s repayment capacity or the risks borne by that buyer’s creditors. Conversely, borrowing is not inherently evidence of a poor investment. The relevant comparison is between the debt’s maturity, the equipment’s useful life and the cash generated by its use.
Nvidia’s November 17 results make the current demand difficult to dismiss. Revenue for the quarter ended October 25 was $115.8 billion, up 103% year on year; Data Center revenue was $107.6 billion, up 110%. Its next-quarter revenue forecast is $130 billion, plus or minus 3%, but includes an additional week and assumes no Data Center compute revenue from China.
A separate Nvidia announcement illustrates the longer commitments behind that demand. Kinsus plans to expand dedicated ABF substrate capacity to more than 3.5 times current levels, with production expected in the second half of 2027 and additional capacity targeted for the third quarter of 2028. A new SPIL agreement, supported by multibillion-dollar Nvidia funding, would increase dedicated advanced packaging capacity by mid-2029. The announcement does not establish that these particular commitments are debt-funded; the ECB’s general warning must not be turned into an unsupported allegation about their financing.
The timing mismatch is economically important. A factory built for several product generations cannot resize itself whenever an AI service changes its tariff. If demand persists, the investment can relieve a capacity shortage. If the user’s revenue arrives later than expected, fixed costs still remain. Capacity-purchase obligations, minimum customer payments, cancellation provisions and responsibility for delays also matter. Today’s releases do not disclose enough of those contracts to pronounce every project sound or unsound.
Software prices can move much sooner. On November 17, OpenAI introduced GPT-6.2 Astra with standard API prices of $8 per million input tokens and $40 per million output tokens, both 20% below GPT-6 Astra. Cached input costs $0.40 per million tokens. That can benefit buyers. But the revenue needed to pay for infrastructure over several years is not determined by the price of one model call: usage volume and cash ultimately collected from customers matter too. A lower tariff does not, on its own, resolve the financing question in either direction.
Consider a hypothetical company selling a customer-support assistant. If it handles the same requests at similar quality with a cheaper model, its margin could improve. If competitors also lower their selling prices, customers receive some of that benefit. If usage expands, processing demand can grow despite the lower price per request. None of those outcomes follows from a tariff table alone. Human review, retries after unsuccessful work and additional tools still contribute to the final cost.
Federal Reserve minutes published on November 18 document a related US concern. They describe the October 27–28 meeting, not a new interest-rate decision. Discussions addressed rapidly growing AI-related debt and complex, circular financing; some participants worried that supervisory data might not fully capture banks’ indirect exposures through nonbank financial institutions. The publication is new, but the participants’ assessments concern information available at that earlier meeting. Reading the minutes as an announcement about conditions first observed yesterday would give the evidence a false chronology.
A hypothetical financing chain makes the issue easier to see without attributing it to any company in this edition. A bank provides a credit line to a fund, the fund finances an operator’s equipment, and the operator relies on a few large customers to meet installments. If one customer reduces its orders, the effect need not stop at that commercial relationship. Understanding the risk requires following payments, guarantees and obligations across the chain. Counting loans explicitly labelled AI would not reveal several borrowers’ dependence on the same customer.
Banks are also users of the technology. An accompanying ECB feature reports that active generative-AI use among euro-area banks rose from 46% in 2024 to 86% in 2025, based on supervisory data; this is not a measurement of adoption in November 2026. It also examines supplier concentration. The operational implication is a second, distinct question for a bank: what financial loss could follow trouble among technology customers, and which of its own daily activities would stop if a supplier’s service failed or changed?
The ECB nevertheless describes banks’ capital, liquidity and profitability as strong. Combining warnings must not manufacture certainty of a crisis. Cheaper models could broaden useful adoption, and today’s investments could supply the capacity that adoption needs. A practical way to evaluate the risk would compare cash remaining after costs under different prices, utilization and energy costs against repayments, then examine what happens when refinancing becomes necessary. Such a calculation should expose its assumptions rather than embed the desired conclusion. It is a framework for testing a financing case, not an estimate of losses.
The next useful disclosures are infrastructure customers’ cash collections, capacity utilization and debt-renewal terms, rather than simply larger announced spending totals. Buyers of AI services can similarly track cost per accepted task and the ability to continue with another supplier, not just a cheaper tariff. The conclusion is limited: strong demand today does not remove the question of repayment tomorrow. Coverage closes at 09:04 Tehran time on November 19. The research window extends from 30 to 48 hours to include the November 17 US release cycle. This is news analysis, not investment advice.
Cover photograph: European Central Bank headquarters, Frankfurt, by Norbert Nagel, February 18, 2023; not a photograph of yesterday’s event. Source: the photographer’s Wikimedia Commons upload. Cropped, resized and converted to WebP only; the adapted image remains licensed under CC BY-SA 4.0. License: https://creativecommons.org/licenses/by-sa/4.0/ ; original photo page: https://commons.wikimedia.org/wiki/File:European_Central_Bank_Frankfurt_Germany_18_Feb_2023.jpg
TagsEuropean Central BankAI financingCredit riskNVIDIAModel pricingBanking
US stocks lost about $6 trillion in 45 days. A widely read analysis calls it a correction, not a burst AI bubble. We checked each claim against filings and market data.
Read More
Databricks plans approximately $3 billion of investment across Europe and the Middle East over three years, including expanded engineering and customer teams.
Read More
Aleph Alpha has released Kolibri, an open-weight model whose small active-parameter count should not be mistaken for a small memory requirement.
Read MoreIf this note maps to a real system in your organisation, start with the services page or a shipped case study.